Senior Underwriter/Senior Vice President
- Denver, CO
From firearms and liquor liability to property, mobile equipment and board governance, sportsmen's clubs require specialized underwriting that standard markets may not be equipped to handle.
Sportsmen's clubs may look like straightforward recreational risks, but many combine firearms, property, liquor, special events, board governance, mobile equipment and member-to-member liability exposures on a single account. These organizations vary widely and can include everything from hunting and fishing clubs to local shooting ranges, with membership ranging from a handful to several thousand members.
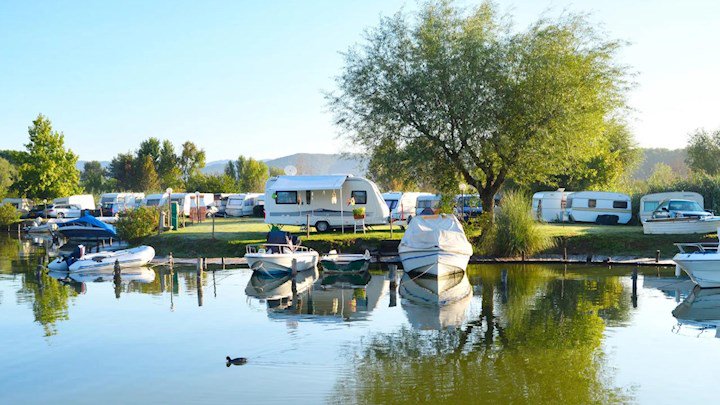
Many clubs include rifle and pistol ranges, trap and skeet fields, archery facilities, clubhouses, restaurants or bars, overnight lodging and fishing lakes. Clubs may also host special events, including fishing tournaments, club dinners and other gatherings that bring members and guests onto the property.
"Sportsmen's clubs are a place where people, and often their families, come to enjoy the outdoors, recreation, and relaxation," says Stephanie Verseman, RPS Senior Vice President and Program Director.
"And when you take a closer look at everything that's happening on these properties, there are many different exposures that need to be considered."
Common exposures may include:
For agents, the challenge isn't simply identifying the exposures, but finding a market that understands how these clubs operate.
A General Liability policy is the foundation of a strong insurance program, protecting the club against third-party bodily injury and property damage claims arising from its operations. An important consideration here is member-to-member liability; club members may be included as additional insureds, providing protection when one member accidentally injures another or damages someone else's property.
Other coverages help round out the risk solution. Liquor Liability may be needed when you serve alcohol. Property insurance protects clubhouses, restaurants, maintenance buildings and other structures, while Inland Marine coverage can respond to mobile equipment such as tractors, backhoes and ATVs used to maintain the property. Many clubs also purchase Umbrella Liability to provide additional protection above their primary liability limits.
One frequently overlooked coverage is Directors & Officers (D&O) Liability, according to Verseman.
"Many sportsmen's clubs are governed by boards that make financial and operational decisions for the organization. D&O coverage helps protect board members against claims alleging wrongful acts in managing the club," she explains.
The greatest distinction between sportsmen's clubs and many other recreational risks is their firearms exposure. Firearm-related incidents are among the most significant claims these clubs can experience.
"Losses can involve one member accidentally injuring another, a firearm that misfires or malfunctions, or a shot that damages neighboring property, including livestock or buildings," says Verseman. "These are exactly the kinds of situations a General Liability policy is designed to address."
However, according to Verseman, relatively few insurers will insure these operations because they require specialized underwriting. That limited market appetite can leave agents facing longer placement timelines, fewer viable options and a greater risk of uncovered exposures.
"Many clubs tell us they've spent months trying to find a market willing to insure them. Once they find us, that search is over."
Sportsmen's clubs can be challenging to insure not because of their size, but because relatively few insurance markets specialize in their unique exposures. A single club may combine recreational activities, firearms, property, mobile equipment, liquor, special events and governance exposures, all of which need to be evaluated as part of the overall risk.
The aforementioned firearm exposure is a major example of where specialized knowledge matters.
"When agents work with an underwriting team that understands these risks, they gain the benefit of experience with firearms exposures, regulatory considerations, and the coverage details that can make a meaningful difference in placement," Verseman says.
Have a sportsmen's club account that needs a specialized market? Work with the RPS Outdoor/Recreation Program team for experienced underwriting insight, thoughtful risk evaluation and a solution designed around how the club operates to best protect its interests.
The information contained herein is offered as insurance industry guidance and provided as an overview of current market risks and available coverages and is intended for discussion purposes only. This publication is not intended to offer financial, tax, legal or client-specific insurance and risk management advice. Any description of insurance coverages is not meant to interpret specific coverages that your company may already have in place or that may be generally available. General insurance descriptions contained herein do not include complete insurance policy definitions, terms and/or conditions, and should not be relied on for coverage interpretation. Actual insurance policies must always be consulted for full coverage details and analysis. Risk Placement Services, Inc. IL License No. 100294602 DBA in California as Risk Placement Services Insurance Brokers. CA License No. 0C66724.